
We're down to the wire and we may not be able to close by 12/30, all because my loan processor is a freaking, lying, incompetent idiot.
On December 16, my loan processor inquired whether she can charge $85 on my credit card for an HOA questionnaire fee. I authorized the charge.
Last Friday, on December 23, I was contacted by my insurance agent that my lender requested Evidence of Insurance. I authorized payment on my credit card and my agent submitted a binder to my lender.
On Tuesday, December 27, my loan processor advised that all documents were received and that my file was with the underwriter for final approval.
On Wednesday morning, December 28, my loan processor advises that she needs me to authorize another credit card charge for an HOA certification for the second association. This time, she doesn't advise me of the charge amount in advance. When I inquired, the charge was $217. I discover that the charge includes an expediting fee. When I inquired why she didn't order the documents back on the 16th, she dances around the issue and blames it on the first association for not providing all documentation and the underwriter for not getting back to her until yesterday.
Now, we're scrambling to meet the 12/30/2011 closing deadline placed by the short sale lender. It irritates me that the idiot loan processor neglected to order the necessary documents from both HOAs back on the 16th. Because of her negligence, I may not be able to close in time by the 30th, which has tax implications and other monetary consequences like having to pay 31 days worth of interest in advance. The worst part is this idiot loan processor's failure to admit fault.
Showing posts with label Rant. Show all posts
Showing posts with label Rant. Show all posts
Thursday, December 29, 2011

Sunday, December 11, 2011
Inspection Result of the Short Sale Condo
I had the short sale condominium inspected last week. As expected, the inspector found additional issues that require repairs. Many of the repairs are due to neglect and lack of maintenance by the Seller.
Before I go on to discuss the repair items, I learned something about the Seller that somewhat irritates me. The Seller purchased the home in 1997 for $180,000. In 1999, she was let go from her job that she had for 17 years. She was unemployed for 2 years until 2001. Her next employment only lasted 1 year. The Seller was then unemployed for another 3 years until 2005, where again, she was only able to maintain a job for 1 year. She's been essentially unemployed (or "self-employed") ever since.
In August 2006 (hopefully during the time she was gainfully employed), she refinanced her home to the tune of $375,000. In March 2007 (during her unemployment period), she took out a 2nd mortgage in the sum of $73,000, probably via a NINJA ("no-income, no-job application") loan.
I know I have no right to judge the Seller because I don't know her entire story. But considering that she's had a spotty employment history since 1999, I can't help but to think she was either greedy or irresponsible for refinancing, rather than selling her condo. Personally, if I wasn't confident about having a steady income to repay my mortgage, I would sell my condo. I certainly wouldn't take out a 2nd mortgage during a period of unemployment.
Had the Seller sold in 2006 or 2007, she could have easily sold for $483,000 - $508,000 and broken even or even made a small profit. The Seller instead chose to live off of borrowed money despite her unstable income. She spent $0 on maintaining the condo and it shows. Every repair item that I know I have to make due to "lack of maintenance," sticks in my craw. I guess it infuriates me because I should've asked for a bigger discount during the negotiation. *Sigh* Live and learn, I guess.
Oh... and did I tell you that the Seller is going to get rewarded with an additional $3,000 from the HAFA program? Oh righty. I'm finished ranting and raving.
Anyhow, here are some of the issues the inspector found:
I'm a bit nervous now that I've underestimated what it would cost to make my unit "move-in" ready. I'm getting a dose of home ownership reality before I've even closed.
Before I go on to discuss the repair items, I learned something about the Seller that somewhat irritates me. The Seller purchased the home in 1997 for $180,000. In 1999, she was let go from her job that she had for 17 years. She was unemployed for 2 years until 2001. Her next employment only lasted 1 year. The Seller was then unemployed for another 3 years until 2005, where again, she was only able to maintain a job for 1 year. She's been essentially unemployed (or "self-employed") ever since.
In August 2006 (hopefully during the time she was gainfully employed), she refinanced her home to the tune of $375,000. In March 2007 (during her unemployment period), she took out a 2nd mortgage in the sum of $73,000, probably via a NINJA ("no-income, no-job application") loan.
I know I have no right to judge the Seller because I don't know her entire story. But considering that she's had a spotty employment history since 1999, I can't help but to think she was either greedy or irresponsible for refinancing, rather than selling her condo. Personally, if I wasn't confident about having a steady income to repay my mortgage, I would sell my condo. I certainly wouldn't take out a 2nd mortgage during a period of unemployment.
Had the Seller sold in 2006 or 2007, she could have easily sold for $483,000 - $508,000 and broken even or even made a small profit. The Seller instead chose to live off of borrowed money despite her unstable income. She spent $0 on maintaining the condo and it shows. Every repair item that I know I have to make due to "lack of maintenance," sticks in my craw. I guess it infuriates me because I should've asked for a bigger discount during the negotiation. *Sigh* Live and learn, I guess.
Oh... and did I tell you that the Seller is going to get rewarded with an additional $3,000 from the HAFA program? Oh righty. I'm finished ranting and raving.
Anyhow, here are some of the issues the inspector found:
- Broken garage door hardware;
- Corroded pipes underneath all of the sinks;
- Chipped kitchen sink and broken garbage disposal;
- Damaged fire door;
- Leaky bathroom faucet;
- Dirty and unmaintained air conditioning unit;
- Dirty and unmaintained heating unit;
- Unsealed platform at heating unit;
- Rusted and discolored burners at heating unit;
- Vent pipe at water heater stained;
- Various locations of drywall damage;
- Various locations of ceiling damage.
I'm a bit nervous now that I've underestimated what it would cost to make my unit "move-in" ready. I'm getting a dose of home ownership reality before I've even closed.
Sunday, September 11, 2011
Stiffing Bank of Mom and Dad
I previously wrote that my Snowball Plan will come to a screeching halt now that I'm purchasing a condo. In actuality, I've just revised my Snowball Plan, yet again, to include my anticipated new debts: my mortgage and the down payment lent to me by Bank of Mom.
Come 10/31/2011, my debts will look something like this:
Based upon these estimates, here's my new Snowball Plan ver. 3.0.
I know that the "real" Snowball Plan requires me too pay off my debts in the order of the smallest balance to the largest. I do plan to pay off my smallest debt first, but I'll also be snowflaking $4,000/year to my Bank of Mom debt.
Some would argue that the $4k/year snowflake should be applied to my student loans instead of to Bank of Mom. But I feel that Bank of Mom deserves the not-so-insignificant snowflaking since she was generous enough to lend me the money interest-free. Additionally, my mom's 69. God knows how much longer she'll live. She got a relatively clean bill of health recently so I'm thinking that she'll be good for at least another 10 years. Hence, my goal is to pay off Bank of Mom in 10 years. I guess I should also be prepared to make a balloon payment for the balance in the event my mom's health deteriorates prematurely. The bottom line is, I intend to take my debt to Bank of Mom seriously and will treat it no differently than any other debt to a "real" creditor.
I'm going to switch gears now and I'm going to engage in some catty gossip. My best friend recently confided to me that she and her husband also "borrowed" approximately $20,000 from the husband's parents for their down payment. It's been 8 years and they've paid back $0.00 so far. In the mean time, they've taken vacations, bought a new car and made improvements to their house. My BFF claims she feels guilty for stiffing the in-laws, but not guilty enough to initiate a repayment plan. My BFF further feels that it's her husband's responsibility to make the repayment arrangements since they are his parents.
I'm appalled at my friend's cavalier attitude about how she and her husband are stiffing Bank of Mom and Dad. I guess since her in-laws haven't said a "peep" about being repaid, perhaps the in-laws intended to "gift" the money. Either way, the issue has been swept under the rug and no one is dealing with it.
I'm a bit disappointed with my friend. No matter how you slice it, she and her husband are deadbeats. They're deadbeats because they're stiffing their family members on a significant sum. Even assuming that the in-laws were willing to gift the money, my friend and her husband are deadbeats since they didn't pay taxes on the non-exempt portion of the amount that was gifted to them.
I wonder if the in-laws have forgotten about the "loan"? Or I wonder if it will always stay in the back of their minds that their kid and his wife stiffed them?
Come 10/31/2011, my debts will look something like this:
| 10/31/11 | Fed'l Sub'd Student Loan | $ 50,558.49 | @ 5.125% | Fixed |
|
| Mortgage | $ 274,000.00 | @ 3.875% | Fixed |
|
| Down Payment | $ 68,500.00 | @ 0.000% | Fixed |
|
| TOTAL | $ 393,058.49 |
|
|
Based upon these estimates, here's my new Snowball Plan ver. 3.0.
I know that the "real" Snowball Plan requires me too pay off my debts in the order of the smallest balance to the largest. I do plan to pay off my smallest debt first, but I'll also be snowflaking $4,000/year to my Bank of Mom debt.
Some would argue that the $4k/year snowflake should be applied to my student loans instead of to Bank of Mom. But I feel that Bank of Mom deserves the not-so-insignificant snowflaking since she was generous enough to lend me the money interest-free. Additionally, my mom's 69. God knows how much longer she'll live. She got a relatively clean bill of health recently so I'm thinking that she'll be good for at least another 10 years. Hence, my goal is to pay off Bank of Mom in 10 years. I guess I should also be prepared to make a balloon payment for the balance in the event my mom's health deteriorates prematurely. The bottom line is, I intend to take my debt to Bank of Mom seriously and will treat it no differently than any other debt to a "real" creditor.
I'm going to switch gears now and I'm going to engage in some catty gossip. My best friend recently confided to me that she and her husband also "borrowed" approximately $20,000 from the husband's parents for their down payment. It's been 8 years and they've paid back $0.00 so far. In the mean time, they've taken vacations, bought a new car and made improvements to their house. My BFF claims she feels guilty for stiffing the in-laws, but not guilty enough to initiate a repayment plan. My BFF further feels that it's her husband's responsibility to make the repayment arrangements since they are his parents.
I'm appalled at my friend's cavalier attitude about how she and her husband are stiffing Bank of Mom and Dad. I guess since her in-laws haven't said a "peep" about being repaid, perhaps the in-laws intended to "gift" the money. Either way, the issue has been swept under the rug and no one is dealing with it.
I'm a bit disappointed with my friend. No matter how you slice it, she and her husband are deadbeats. They're deadbeats because they're stiffing their family members on a significant sum. Even assuming that the in-laws were willing to gift the money, my friend and her husband are deadbeats since they didn't pay taxes on the non-exempt portion of the amount that was gifted to them.
I wonder if the in-laws have forgotten about the "loan"? Or I wonder if it will always stay in the back of their minds that their kid and his wife stiffed them?
Tuesday, August 24, 2010
Filing For Bankruptcy
No, not me. The only debt I have right now is my oppressive student loans (~$88k) which can't be BK'd away. *Bleh*
My sister and I hired an attorney to file Chapter 7 bankruptcy on behalf of my parents. Since my parents have absolutely no assets to speak of, the bankruptcy filing is relatively straightforward and simple. I could've done the work since I'm admitted to practice in federal court, but quite frankly, I'm pissed with my parents for being so careless and apathetic about their finances. (In April, they had $60k in credit card debt and had no clue about it!) My sister made valiant efforts to get my parents (or at least my mother) to sit down to discuss a budget, but they couldn't care less. After four months, my sister managed to get my parents' debt down to $55k! But it's only a matter of time before my father will pass away, leaving a crushing debt that is unaffordable under my mother's Social Security survivor's benefits alone. C'est la vie - - my parents will pay a flat fee of $1,895 + $300 filing fee to bankrupt away their debts. I'm not going to pay this cost for them.
Of course, my sister and I will be doing all of the leg-work of compiling information about my parents' debt, their income, their cost-of-living, etc. And the next struggle will be to get my mother to actually undergo credit counseling. (My dad will likely be exempt due to his dementia.) Since my mother never bothered to learn English, I will probably have to attend with her and translate. Joy.

I'm sorry to be complaining here. But I just can't forgive or fathom my parents' attitude that their financial mess is their daughters' responsibility to clean up.
Monday, February 15, 2010
Update - Dealing With My Parents
Wow. Thank you all so much for the outpouring of support and understanding. It really means a lot to me and I'm touched. Although this may sound selfish, I find it somewhat comforting to know that other people are struggling with the same issues I am (and even worse).
Anyhow, my posts in the near term will focus primarily on issues dealing with my parents versus my own finances.
The past couple of weeks have made me want to slam my head into the wall. Not only is it bad enough that my mother allowed my father, who suffers from dementia, to drive, she's been allowing him to handle their finances. She says my father, in a fit of anger and paranoia, took away the handling of their finances from her years ago. Ever since then, she took a "not my problem" attitude and let my father do what he did despite knowing that his dementia was getting progressively worse. She blamed his belligerence and intransigence for her failure to intervene. Again, this is an example of my mother shirking her personal responsibilities and blaming others for her problems.
I'll post my mortifying discoveries in a future post.
I recently took a couple of days off from work to visit my parents' to get some financial and personal housekeeping done. The airfare + car rental + gas cost me $500+. Joy.
Anyhow, here's an update stuff my sister and I've managed to address since my last post:
And this brings me to our To-Do List:
I am currently resentful, angry, disappointed, frustrated and ultimately ashamed of my parents. Please be aware that I'm not feeling this way because they are helpless, poor or ill. I feel this way because they seem resigned and content to do nothing, assuming that my sister and I will take care of them if all goes to pot. They have absolutely no incentive or motivation to try to make things work. In a future post, I will reveal what my mother said to me recently, which made my blood boil and steam come out of my ears.
I really want to take a "not my problem" attitude that my mom was all too happy to take over the years. But I know the longer I ignore this and don't take control, things will only get worse. And my sister and I will have to clean up my parents' avalanche of a mess.
Anyhow, my posts in the near term will focus primarily on issues dealing with my parents versus my own finances.
The past couple of weeks have made me want to slam my head into the wall. Not only is it bad enough that my mother allowed my father, who suffers from dementia, to drive, she's been allowing him to handle their finances. She says my father, in a fit of anger and paranoia, took away the handling of their finances from her years ago. Ever since then, she took a "not my problem" attitude and let my father do what he did despite knowing that his dementia was getting progressively worse. She blamed his belligerence and intransigence for her failure to intervene. Again, this is an example of my mother shirking her personal responsibilities and blaming others for her problems.
I'll post my mortifying discoveries in a future post.

I recently took a couple of days off from work to visit my parents' to get some financial and personal housekeeping done. The airfare + car rental + gas cost me $500+. Joy.
Anyhow, here's an update stuff my sister and I've managed to address since my last post:
- I made copies of my parents' executed durable power of attorney and medical power of attorney and healthcare directive. My mother has made it clear with her actions and words that she has no intention of being my father's attorney-in-fact or agent. That means my sister and I have to step up to the plate.
- I took my father to see his primary doctor. Before the visit, I had my father sign a limited consent form that authorized his doctor to release his medical care information to my sister and me. I gave the doctor a copy of my father's consent form and a copy of his medical power of attorney. I specifically instructed the doctor and his staff that all future communications involving my father should be with my sister or me.
- I drove my father to the DMV to surrender his driver's license and to obtain a state-issued ID. During the visit, he also surrendered his license plate, where he would receive ~$54 back.
- I then drove my parents' to see their auto insurance agent. During the visit, my parents signed a proof of loss and other collision-loss related documents. Their insurance company agreed to cover the loss of my parents' car for $12,506.15 minus $500 deductible minus payoff of car loan (est. $6,000). Looks like my parents won't have to worry about paying back the car loan. The insurance company is also dealing with the PD claim to the brick wall/store sign that my father plowed into. This claim is still pending.
- Got my parents a Reduced Fare ID so they can take public transportation for 50% of the regular fare.
- Toured an adult daycare facility with my parents. I told my father that we are planning to send him to such a facility to give my mother some respite care and to give him some "stimulation" that he claims he is seriously lacking in his life. My father seemed okay with the idea but my mother was clearly displeased. I've estimated that the cost will run approximately $72/day, including food and transportation. My sister and I are still crunching numbers as to how much my parents can afford to cover this cost until he qualifies for Medicaid.
And this brings me to our To-Do List:
- Go through my parents' finances to determine their assets and liabilities and their monthly income. This will help us determine whether my parents will qualify for Medicaid.
- Schedule a physical for both my mother and father so that they will be ADA (Americans With Disabilities Act) certified. Fill out ADA Service Eligibility application so that they will both get priority treatment when they use the Dial-A-Ride service.
- Schedule appointments with my father's pulmonary specialist and neurologist and give them copies of his medical power of attorney and authorization to contact my sister and me.
- Contact my parents' CPA and ask for copies of their past tax returns. If not, contact IRS. Verify whether my parents owe back taxes and/or penalties.
- Apply for Medicaid and Medicaid Long Term Care System. Medicare generally does not cover for long term care costs such as nursing homes or adult daycare. Medicaid is a State and Federal Government program that pays for some long-term care services at home and in the community. Who is eligible and what services are covered vary from state to state. Most often, eligibility is based on income and personal resources.
- Apply for state/community-based subsidized or free programs that encourage senior independent living, such as S.A.I.L.
- Apply for volunteer-based programs that provide free transportation.
I am currently resentful, angry, disappointed, frustrated and ultimately ashamed of my parents. Please be aware that I'm not feeling this way because they are helpless, poor or ill. I feel this way because they seem resigned and content to do nothing, assuming that my sister and I will take care of them if all goes to pot. They have absolutely no incentive or motivation to try to make things work. In a future post, I will reveal what my mother said to me recently, which made my blood boil and steam come out of my ears.
I really want to take a "not my problem" attitude that my mom was all too happy to take over the years. But I know the longer I ignore this and don't take control, things will only get worse. And my sister and I will have to clean up my parents' avalanche of a mess.
Monday, December 14, 2009
Are You Sure FICO isn't spelled FYCO?
I think the acronym for FICO should be changed to FYCO, because it sure seems to be sending a clear message that it doesn't think much about me.
(Before I go on my tirade, I bought my FYCO score on myFICO.com with a 30% off coupon, promotion code: SURVEY30. If any of you are looking to get your scores, hope this code works for you as well.)
After my self-congratulatory post last Friday about paying off my cc debt, I admit I was feeling mighty smug that my FYCO score would be darn awesome. (After all, my CreditKarma score is 801!) But instead, I got a cold splash of reality last Friday when I learned my new FYCO score is:

The last time I got my FYCO score in May, it was 723.
Granted, the last FYCO score was based on Equifax's data and this credit score is based on TransUnion's data. But the data is pretty consistent between the two. You could also argue that the difference between 719 and 723 is de minimis, but here are several reasons why I think this whole FYCO scoring system is bogus:
1.) Paying Off My Huge Revolving Credit Card Debt Did Bupkis
One of the negative issues in May was that I was using too much (i.e., 18%) of my available credit limit. I didn't disagree with this negative mark since I had over $11k+ in credit card debt at the time. But as you know, I paid that debt off in October and am now only using 2% of my available credit limit.
Considering the fact that FYCO claims "usage ratio" plays a big factor in its secretive scoring formula, paying off a huge cc debt didn't do me much good. Do you want to know what FYCO is nit-picking about now?
I allegedly have too many accounts (11) with balances. First off, 6 of the 11 accounts are my student loans. The remaining 5 accounts only have balances between $26 to $1,613, which I already paid off in full this month.
In case you were wondering why I have 5 accounts with balances, it's because I'm splitting my cc usage over multiple cards so that I don't get dinged with "inactive" penalties like fees, reduced credit limit or outright cancellation by the cc companies.
Bottomline - - If I don't use my cards, I get penalized with fees and reduced limits by the cc companies, but if I use my cards responsibly, FYCO beats me up for it. Lovely!
2.) FYCO's Infernal (and Eternal) Scarlett Letter
I was always under the belief that a bad credit rating doesn't stick around forever. I believed that negative information (such as late payments) would fall off 7 years from the date the payment was late. Boy was I wrong! Apparently, FYCO still takes that information into consideration. For example:
TransUnion's data on one of my account indicates:
But guess what? It also says:
I guess my late payment history WILL haunt me forever and ever. It reminds me of this tasteless joke:
3.) FYCO Simulator is a Joke
Here's a joke: FYCO's simulator claims I can dramatically improve my score to 779 to 819 if I pay off 90% to 100% of my credit card balances! Uhhhhh... Yeah, sure.
Considering that my elimination of $11k in cc debt didn't do me much good, I doubt paying off my current credit card balances of <$2,000 in full every month will dramatically increase my score by about 60 to 100 points. Yeeeahhhhh....
And here's another sick joke: Back in May, FYCO's simulator predicted my score would increase to 723-763 if I paid off my $11k+ credit card debt within 6 months. Ummmm.... it's been 6 months and I paid off that debt. But my FYCO score did a backslide instead. What gives?
I am now pretty discouraged that I will forever have to live with a "below average" credit score. Perhaps I should rename this blog to "Hester Prynne's PF Blog"...
(Before I go on my tirade, I bought my FYCO score on myFICO.com with a 30% off coupon, promotion code: SURVEY30. If any of you are looking to get your scores, hope this code works for you as well.)
After my self-congratulatory post last Friday about paying off my cc debt, I admit I was feeling mighty smug that my FYCO score would be darn awesome. (After all, my CreditKarma score is 801!) But instead, I got a cold splash of reality last Friday when I learned my new FYCO score is:

The last time I got my FYCO score in May, it was 723.
Granted, the last FYCO score was based on Equifax's data and this credit score is based on TransUnion's data. But the data is pretty consistent between the two. You could also argue that the difference between 719 and 723 is de minimis, but here are several reasons why I think this whole FYCO scoring system is bogus:
1.) Paying Off My Huge Revolving Credit Card Debt Did Bupkis
One of the negative issues in May was that I was using too much (i.e., 18%) of my available credit limit. I didn't disagree with this negative mark since I had over $11k+ in credit card debt at the time. But as you know, I paid that debt off in October and am now only using 2% of my available credit limit.
Considering the fact that FYCO claims "usage ratio" plays a big factor in its secretive scoring formula, paying off a huge cc debt didn't do me much good. Do you want to know what FYCO is nit-picking about now?
I allegedly have too many accounts (11) with balances. First off, 6 of the 11 accounts are my student loans. The remaining 5 accounts only have balances between $26 to $1,613, which I already paid off in full this month.
In case you were wondering why I have 5 accounts with balances, it's because I'm splitting my cc usage over multiple cards so that I don't get dinged with "inactive" penalties like fees, reduced credit limit or outright cancellation by the cc companies.
Bottomline - - If I don't use my cards, I get penalized with fees and reduced limits by the cc companies, but if I use my cards responsibly, FYCO beats me up for it. Lovely!
2.) FYCO's Infernal (and Eternal) Scarlett Letter
I was always under the belief that a bad credit rating doesn't stick around forever. I believed that negative information (such as late payments) would fall off 7 years from the date the payment was late. Boy was I wrong! Apparently, FYCO still takes that information into consideration. For example:
TransUnion's data on one of my account indicates:
Seven year payment history
| 30 days late | 0 times |
|---|---|
| 60 days late | 0 times |
| 90+ days late | 0 times |
But guess what? It also says:
Worst Delinquency
| 90 days past due |
| The Worst Delinquency reports the worst missed payment status that has been documented on this account. Your FICO® score evaluates how recently that missed payment occurred and in general, the more recent, the more impact it has on your score. However, the fact that it occurred is still predictive of future payment risk and could be considered by your FICO® score. |
I guess my late payment history WILL haunt me forever and ever. It reminds me of this tasteless joke:
This Scottish farmer walks into the neighborhood pub, and orders a whiskey.
"Ye see that fence over there?" he says to the bartender. "Ah built it with me own two hands! Dug up the holes with me shovel, chopped doon the trees for the posts by me ownself, laid every last rail! But do they call me 'McGregor the Fence-Builder?' No..."
He gulps down the whiskey and orders another. "Ye see that pier on the loch?" He continues, "Ah built it me ownself, too. Swam oot into the loch to lay the foondations, laid doon every single board! But do they call me 'McGregor the Pier-Builder?' No."
"But ye #$&! just ONE lousy sheep ..."
3.) FYCO Simulator is a Joke
Here's a joke: FYCO's simulator claims I can dramatically improve my score to 779 to 819 if I pay off 90% to 100% of my credit card balances! Uhhhhh... Yeah, sure.
Considering that my elimination of $11k in cc debt didn't do me much good, I doubt paying off my current credit card balances of <$2,000 in full every month will dramatically increase my score by about 60 to 100 points. Yeeeahhhhh....

And here's another sick joke: Back in May, FYCO's simulator predicted my score would increase to 723-763 if I paid off my $11k+ credit card debt within 6 months. Ummmm.... it's been 6 months and I paid off that debt. But my FYCO score did a backslide instead. What gives?
I am now pretty discouraged that I will forever have to live with a "below average" credit score. Perhaps I should rename this blog to "Hester Prynne's PF Blog"...
Tuesday, December 1, 2009
An Annoying Expense
No, I'm not talking about car repairs or Swiffer refills. I'm talking about having to replace my "fat" (not phat) jeans. My one and only pair of jeans that fit me, has given up its ghost. I now need to replace it.
About a couple of years ago, I was invited to an old college friend's wedding. He happens to be a childhood buddy of my ex, so I knew the ex would be at the wedding. I dreaded seeing my ex, not because we had a horrible break-up, but because I had gained 25 lbs since our break-up.
Now mind you, I'm not fat. I'm relatively slender, compared to the average American woman. I was also extremely skinny while I was dating my ex during college (approx. 95 lbs).
 Although I didn't have any residual feelings for my ex, my vanity couldn't allow him to see me 25 lbs heavier. I started exercising regularly and went on a strict diet. I managed to bring my weight down by 15 lbs. I was pretty happy being 105 lbs and I thought I looked pretty good! I was pretty certain that I could maintain this weight and got rid of a lot of my "fat" clothes.
As they say, the best laid plans of mice and men. Now that the wedding has come and gone, I lost motivation to keep exercising. (See the "exercise jar" on the right sidebar?) I've also started "emotional eating". And guess what? I'm back to my pre-wedding weight. **Sigh**
I guess I could try to squeeze myself into my "skinny" jeans. But I'm afraid of creating an unsightly muffin top. Or worse yet, a cracked muffin top.

I guess I have 2 options: (1) buy a replacement "fat" jeans, or, (2) lose weight.
I'm just not sure which route to take...
About a couple of years ago, I was invited to an old college friend's wedding. He happens to be a childhood buddy of my ex, so I knew the ex would be at the wedding. I dreaded seeing my ex, not because we had a horrible break-up, but because I had gained 25 lbs since our break-up.
Now mind you, I'm not fat. I'm relatively slender, compared to the average American woman. I was also extremely skinny while I was dating my ex during college (approx. 95 lbs).
 Although I didn't have any residual feelings for my ex, my vanity couldn't allow him to see me 25 lbs heavier. I started exercising regularly and went on a strict diet. I managed to bring my weight down by 15 lbs. I was pretty happy being 105 lbs and I thought I looked pretty good! I was pretty certain that I could maintain this weight and got rid of a lot of my "fat" clothes.
As they say, the best laid plans of mice and men. Now that the wedding has come and gone, I lost motivation to keep exercising. (See the "exercise jar" on the right sidebar?) I've also started "emotional eating". And guess what? I'm back to my pre-wedding weight. **Sigh**
I guess I could try to squeeze myself into my "skinny" jeans. But I'm afraid of creating an unsightly muffin top. Or worse yet, a cracked muffin top.
I guess I have 2 options: (1) buy a replacement "fat" jeans, or, (2) lose weight.
I'm just not sure which route to take...
Tuesday, November 17, 2009
United Did Right By Me
I recently emailed United Airlines to complain about an overcharge for an in-flight meal I didn't purchase. What I didn't mention in my prior post was that I also complained about the malfunctioning sound system on my flight. (I had to watch Julie & Julia in Español.)
I'm actually surprised that I got a response from United's customer service department.

What's interesting is that United appeared more concerned about the malfunctioning sound system than the overcharge. United's customer service rep started off his email with:
As a good will gesture, United gave me a $100 travel voucher for future travel. The customer service rep also indicated that United will be issuing me a check for $9 to reimburse me for the overcharge. Hurray!
I cautioned that we should all check our receipts at the time of purchase. But it always helps to voice our complaints. If the company values your business, they will do you right. Even if it's an airline.
I'm actually surprised that I got a response from United's customer service department.

What's interesting is that United appeared more concerned about the malfunctioning sound system than the overcharge. United's customer service rep started off his email with:
"We realize that any type of malfunction can impact your perception of our overall operation. Please know that we place a great deal of emphasis on proper maintenance of all equipment in our cabins. In fact, our maintenance division has recently completed an audit of each fleet type and taken inventory of problems. Based on that we have established a program to check the cabins of each aircraft every 400 to 1,000 flight hours. We will be identifying and repairing seats, carpets, galley equipment, lights and audio and video equipment. In addition, another maintenance team is concentrating on cleaning methods, audio and video functionality and improved cabin condition monitoring. Still, your disappointment with your flight is understandable, and I will give your constructive feedback to our maintenance and onboard management because we are committed to providing you a positive in-flight experience."
As a good will gesture, United gave me a $100 travel voucher for future travel. The customer service rep also indicated that United will be issuing me a check for $9 to reimburse me for the overcharge. Hurray!
I cautioned that we should all check our receipts at the time of purchase. But it always helps to voice our complaints. If the company values your business, they will do you right. Even if it's an airline.
Friday, November 13, 2009
Always, Always Check Your Receipt
I've been on a business trip to the Big Easy for the past couple of days. I ate a huge Po-Boy sandwich for lunch, so I wasn't hungry before my return flight. But, of course, the moment I boarded the plane, my stomach started to rumble. Because airline food look less appetizing than the plastic food displays at family restaurants in Japan, I never order them.

But last night, I decided to buy an Antipasto meal ($7) on my United flight. (How bad could salami, cheese and breadsticks be?) Since United no longer accepts cash for in-cabin purchases, I used my credit card to purchase the item. The cabin was dark and I was tired, so I grabbed the receipt and scarfed down the "meal."
When I got off the plane, I finally looked at my receipt. And there it was -- I also got charged for a Thai Chicken Wrap ($9) that I didn't purchase. Although I was ticked off with United about this overcharge, I was more p.o.'d with myself for not checking my receipt while I was on board.
When I got home (after midnight, FYI), I fired up my computer and emailed a complaint to United. Surely if they took an inventory of their food supply for that flight, they must find that they overcharged me, right? I demanded a refund.
I know airlines are nickel-and-diming its passengers for an extra buck, but I hope they're not trying to make an extra buck by stealing. We'll see if United does me right on this. I got an automated response that they will respond within 5 business days. I'll keep you posted.
Friday, November 6, 2009
Greedy Daughter Post -- Cont'd
In my prior post, I wrote, "I told my sister that ... if she [buys a rental property and rents to our parents], SHE will have to be the one to take care of our parents when there's an emergency. I should not be looked upon to care for my parents, especially if I'm not getting any money from parents." Some of you thought this was callous and cold, but also gave me the benefit of the doubt. So I guess some background information is in order.
My sister gets transferred around the country quite frequently by her employer. And by the nature of the work she does, she rarely gets to live in big cities. She often has to live in the ex-burbs (i.e., the sticks) where the closest airport may be about a 30 to 50 mile drive away. Over the past 10 years, she's lived in Maryland, Washington, Alabama and Texas. She is now moving to Arizona. I, on the other hand, have stayed put in San Diego for the past 9 years.
My sister has a strong personality and, in my opinion, is often not very empathetic. In some ways, she may just be more honest and upfront about airing her frustrations about our parents to their face than I. (I just rant and rave about them on my blog behind their backs. So perhaps I'm just two-faced.) My mom once confided in me that she often finds being alone with my sister a bit "unpleasant."
My parents have really never had any real emergencies in the past that required any significant assistance from my sister or me. But I know that my parents are now at an age where emergencies will arise, whether it's health related or financial. I also know that I'll probably be the one that gets the first call for assistance. Will I ever tell my parents to take a hike if they pay rent to my sister? Of course not.
I guess I made the comment to put my sister on notice that she can't use distance or inconvenience as an excuse to lay the lion's share of my parent's care on me. I especially feel this is true if her mortgage is going to be subsidized by our parents.
But some of the comments I received were enlightening. It never occurred to me that the landlord-renter relationship may not be as easy as I think it is. This would especially be true if my parents defaulted on their rent. (After all, they almost stiffed me in the past during financially tough times.) I guess I could also see friction arising if there are any disagreements about maintenance and upkeep of the property.
Bottomline is, family is family and fighting over money is really self-defeating and pointless.

Upon further reflection, I guess this was just a tangential rant about a more deep-seated fear of mine - - when and how much will I have to care for my parents in their old age?
Wednesday, October 14, 2009
What Is the Value of a Massage Service Received?
During the past couple of months, I took an extended leave from blogging to deal with chronic neck pains and insomnia by seeing a chiropractor and a physical therapist. In August, I considered adding a monthly massage into my therapy since I knew I was very close to paying off my credit card and I could afford it. (To those who are thinking I should pay down my student loans rather than get massages, let me rephrase: I could afford to pay for monthly massages without going back into credit card debt. Mmm-kay?)
 One weekend in August, I went to a chi-chi resort in La Jolla that charged $130 for a 50 minute massage. The spa facilities were fancy-shmancy and I loved it. The massage on the hand could only be described as... "meh."
In September, while in Chicago, I got a massage at a five-star hotel near Michigan Avenue. (It was the only spa that would take me on a Sunday evening as a walk-in. I swear!) The ritzy spa charged $135 for a 50 minute massage. The facilities were gorgeous but again, the massage itself was, "meh."
In both instances, I tipped the massage therapists $26 and $27 respectively, notwithstanding the mediocre quality of the massages I received.
For my October massage, I was thinking about scheduling a $79 service at my chiropractor's office, but was enticed by a $49 (50 min.) massage special at Massage Envy instead. For those who aren't familiar with Massage Envy, it's a "membership spa" where members pay $59/month (or whatever price the franchisee set) and get one (1) 50-minute massage per month. Members can get additional 50-minute massages in the same month for $39 a pop. Non-members pay $98 per 50-minute massage.

I was initially turned off by the fact that Massage Envy's "spa" didn't have any showering facilities or a steam room. (Uhhh... I really think a business that calls itself a spa should at least have some kind of water related facility, but I digress.) Nevertheless, I gave it a whirl and was pleasantly surprised at the quality of the massage I received. It certainly kicked serious butt of the chi-chi resort massages I previously got. I signed up for a 6 month membership.
But when it came time to pay the tip, I froze. Massage Envy's tipping guidelines suggested $14-$20, but I wondered about some of the same things that financial writer, Liz Pulliam Weston, did in this article.
I initially wondered whether a $12 tip (i.e., 20% x the regular member's price of $59) would have sufficed as a decent tip? But why should the mediocre massage therapists at the chi-chi resorts get double for the same service? On the other hand, since I don't enjoy the same luxe facilities at Massage Envy that I get at the tony resorts, doesn't that mean I can tip less?
After what seemed like an eternal internal debate, I left a $17 tip. I justified the tip based upon prices that other non-membership "day spas" (that also lack showering facilities) charge for a 50 minute massage. The prices in San Diego range from $65 to $80, so I think a $14 to $17 tip is quite appropriate for a 50-minute massage. (Liz Pulliam Weston's neighborhood really has $39 massages?)
This begs the question: Can an establishment really set the perceived value of a service delivered? I don't think so. I compare places like Massage Envy to car washes that offer cut rate prices at the expense of their employees. Just as I do at car washes, when I think an employee may be underpaid, I tip based upon the value of the service I think I received, not what I was charged. In other words, I tip beyond the 20% standard. I really can't be angry at Massage Envy's tipping guidelines since it benefits the therapist, not the franchisee.
But now I'm starting to regret - - if I suspect an establishment isn't paying its employees a decent wage, maybe I shouldn't be patronizing the business at all... *Cr&p*
Tuesday, August 25, 2009
Thank You For Your Kind Words! I'm Officially Stuck In The Fifth Ring of Hell
Sorry all for the long absence! I've been going through physical therapy and undergoing chiropractic care, which has helped quite a bit with the headaches and neck pains.
Just as I thought things were going well... Well... I'm now stuck in the fifth ring of hell, so to speak.
My company underwent a management overhaul this past year, and let's just say the new regime is trying to make an imprint. And by imprint, they're forcing us peons to undergo Gawd-awful team building exercises. You know the ones I'm talkin' about. In case you're fortunate enough never to have experienced this excruciatingly mind-numbing time-sink, watch this American Airlines commercial and you'll understand.
The worst part about this is that I'm forced to fly cross-country almost every other week this month to participate. I feel like I've joined a cult that deprives me of sleep to make me vulnerable and confused, so that I'll voluntarily drink the Kool-Aid. Please don't ask me what the logic to this is, since I don't see any.
I'm also not going to say much more about this since, God forbid, someone at my company reads this blog. But more than that, when so many people are currently unemployed, it just seems very petty and shallow of me to whine about it.
Anyhow, the constant travels has put me seriously behind the eight-ball at work and I've been a bit overwhelmed. The brainwashin.... errrr... the team building exercises should be over by end of September. Thank you all again for your kind thoughts and words. Rest assured, I'm better now. Well... atleast physically, so I will be back soon! (I hope...)
Thursday, July 9, 2009
Ink Jet Cartridge Refill Fail
So I've been reading about how wonderful it is to refill your ink cartridges at a fraction of the cost you would pay to buy new cartridges. Walmart sells my black + color ink cartridge combo for $47.97 + tax. $52 is a bit steep, so I decided to give the refill a try at Costco, whose refill price ranges between $7.99 - $14.

First of all, it's not all THAT easy. I went to Costco and was told it would take an hour. Ummmm... okay. I was hoping it would be more like 15 minutes, so I can go around the store trying freebie food samples while I waited. No problem, I'll come back in an hour.
An hour later, I was told that the refill for my color cartridge didn't work. (Grrrr.) I was charged $7.99 + tax for the black cartridge refill. Oh, and the Costco guy tried to keep my color cartridge.
Costco Dude: You want the empty cartridge back?
Shtinky: Duh, dude. I can get a $3 rebate from Staples if I do so.
Now I'm off to Staples to buy myself a color cartridge for $28.99 + tax. (I bought the cartridge at Staples for no other reason than convenience.) I recycled my cartridge and was told I'll get my $3 rebate some time before the end of the year. Great.
Once I got home, my printer recognized my new color cartridge but indicated that my black cartridge was empty. WTF? No matter what I did, it still showed the black ink cartridge was empty. *Annoyed sigh*
I returned to Costco to complain. The Costco counter dude asks, "Didn't you read our instructions?"
Shtinky: WHAT instructions?
Costco Dude: This one. [Shows me a print-out of Do's and Don't's of Inkjet Catridge Care and Maintenance that says: 'After inserting the refilled cartridge, some printers may indicate a "Low Ink" message. For help with this or other printer related matters please visit: www.inkjet411.com']
Shtinky: It would've been nice if you would've given me that before I left the store.
Costco Dude: We always include it with our refills. You probably misplaced yours.
I was sufficiently annoyed that I decided to return the refilled ink cartridge for a refund. But of course, Costco kept the black ink cartridge, so I couldn't recycle it for another $3 rebate. I then went to Walmart to pick up a new black ink cartridge for $23.97 + tax.
FINAL TALLY OF MY INK JET CATRIDGE REFILL FAIL
Color Cartridge: $31.53
Black Cartridge: $26.07
Missed Opportunity to Recycle Black Cartridge: $3.00
Unnecessary Gas Usage + Mileage (Driving to and fro Costco-Staples-Walmart): $2.00 (est.)
SUBTOTAL: $62.60
And keep in mind, I could've just purchased a combo pack for $52.16 and gotten a $6.00 rebate from Staples for future ink cartridge purchases.
Total Money Saving Fail: $16.44
I could've bought couple of nice lunches or atleast 1 dinner with this lost money.
Grrrrrr... I may try to refill again in the future and see if I'll have better luck next time.
Monday, June 22, 2009
Stupid Excel Virus Ruined My Weekend
I previously wrote about my insane accounting to keep track of my 7 savings and 3 checking accounts. I don't use financial programs like Quicken or the new-fangled, fancypants online services like Wesabe or Mint. Nope. My insanity is memorialized in my trusty Excel spreadsheet and this blog.
Unfortunatley, looks like at some point, my trusty sidekick became infected with a heuristic virus.
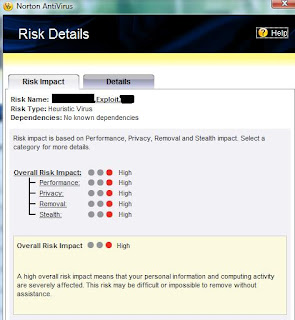
Ugggghhhh! I used my anti-virus program to scan the program and good ol' Norton removed/quarantined the stupid infection. But I couldn't open my spreadsheet anymore. GAAAAAAAHHHH!!!
If that wasn't bad enough, ever since I've discovered my spreadsheet was infected by the virus, some douche-bag in China has been attempting to hack into my computer.
How could this happen to me? I don't download programs, music or movies! When it comes to my computer, I pretty much wear the techno-equivalent of the Jo-Bro purity ring!
I digress, ahem.
The last time I created a "back-up" of my spreadsheet was in January and I've spent the entire weekend re-creating my financial data for the past 6 months. Thank goodness for my blog, since I was able to find most of the info here. I really think there's a special ring of hell for jerks who create computer viruses.
Unfortunatley, looks like at some point, my trusty sidekick became infected with a heuristic virus.

Ugggghhhh! I used my anti-virus program to scan the program and good ol' Norton removed/quarantined the stupid infection. But I couldn't open my spreadsheet anymore. GAAAAAAAHHHH!!!

If that wasn't bad enough, ever since I've discovered my spreadsheet was infected by the virus, some douche-bag in China has been attempting to hack into my computer.
How could this happen to me? I don't download programs, music or movies! When it comes to my computer, I pretty much wear the techno-equivalent of the Jo-Bro purity ring!
I digress, ahem.
The last time I created a "back-up" of my spreadsheet was in January and I've spent the entire weekend re-creating my financial data for the past 6 months. Thank goodness for my blog, since I was able to find most of the info here. I really think there's a special ring of hell for jerks who create computer viruses.
Wednesday, June 3, 2009
The Best Of the Worst Home Buying Advice I've Received Over the Years
As someone who's never owned my own home before, I get a lot of unsolicited advice from others. I'm glad I march to the beat of my own drummer since many of these advices are just plain imprudent.
Advice I'm Glad I Never Took #1
From my prior post:
Yeah. Your broker would have given me a negatively amortizing, option ARM, subprime loan and I'd be homeless now.
Lesson Learned: If it sounds too good to be true, it probably is.
Advice I'm Glad I Never Took #2
During the housing bubble heyday, several people told me I should take money out of my 401k and plunk it in real estate. "You're taking money from one investment to another -- One that will NEVER lose money!" Uh-huh.
One friend told me that her single friend took money out of her 401k to buy a 1 BR condo. She said I should do the same since I'm pissing money away in rent on a 1 BR apartment anyways. Fast foward to now: That single friend is now married, moved to Northern California and let her 1 BR condo go into foreclosure.

Lesson Learned: Don't tap into your 401k to buy property because that's a clear sign that you can't afford the home.
Advice I'll Never Take #1
I have a co-worker who bought a home beyond his means. Last September, he was fretting that his mortgage will re-adjust in April. He couldn't afford to refinance since his loan is a jumbo loan and the mortgage rates are more than his adjustable rates are. He was thinking about refinancing to a 5-year interest-only loan.
Anyhow, he advised me that when I buy my first home that I shouldn't be discouraged if it's a small place. He suggested that I keep trading up like him. Ummmm... Yeah... No offense, but I don't think this guy is a role model.
Lesson Learned: Don't keep trading up if you can't afford it.
Advice I'll Never Take #2
Remember Co-Worker #1 from above? He said that he uses his second home like a piggy-bank. Every time the value of the home goes up, he takes money out. Since it's his second home, I guess it isn't as bad as what another friend has done to his primary home. (It's still bad advice, though.)
Below is a true and graphical example of what this other friend did. It's a picture perfect example of "what not to do with the equity in your own home".
Lesson Learned: Your house isn't a piggy bank!
Advice I'm Glad I Never Took #1
From my prior post:
Co Worker #1: "Shtinky, you need to buy yourself a property – ANY property..."
Shtinky: “I can’t afford it with my student loan payments.”
Co-Worker #1: “Yes you can! Just talk to my broker. He’s got so many amazing mortgages he can offer you. You can get a mortgage where your monthly payments will be around where your rent payments are! And besides, you’ll get tax deductions and you can pay off your student loans with your mortgage!!”
Yeah. Your broker would have given me a negatively amortizing, option ARM, subprime loan and I'd be homeless now.
Lesson Learned: If it sounds too good to be true, it probably is.
Advice I'm Glad I Never Took #2
During the housing bubble heyday, several people told me I should take money out of my 401k and plunk it in real estate. "You're taking money from one investment to another -- One that will NEVER lose money!" Uh-huh.
One friend told me that her single friend took money out of her 401k to buy a 1 BR condo. She said I should do the same since I'm pissing money away in rent on a 1 BR apartment anyways. Fast foward to now: That single friend is now married, moved to Northern California and let her 1 BR condo go into foreclosure.

Lesson Learned: Don't tap into your 401k to buy property because that's a clear sign that you can't afford the home.
Advice I'll Never Take #1
I have a co-worker who bought a home beyond his means. Last September, he was fretting that his mortgage will re-adjust in April. He couldn't afford to refinance since his loan is a jumbo loan and the mortgage rates are more than his adjustable rates are. He was thinking about refinancing to a 5-year interest-only loan.
Anyhow, he advised me that when I buy my first home that I shouldn't be discouraged if it's a small place. He suggested that I keep trading up like him. Ummmm... Yeah... No offense, but I don't think this guy is a role model.
Lesson Learned: Don't keep trading up if you can't afford it.
Advice I'll Never Take #2
Remember Co-Worker #1 from above? He said that he uses his second home like a piggy-bank. Every time the value of the home goes up, he takes money out. Since it's his second home, I guess it isn't as bad as what another friend has done to his primary home. (It's still bad advice, though.)
Below is a true and graphical example of what this other friend did. It's a picture perfect example of "what not to do with the equity in your own home".

Lesson Learned: Your house isn't a piggy bank!
Wednesday, May 27, 2009
Out of Sync with Reality
If there's anything this recent economic crisis taught me, it's that when things are out-of-sync with or disconnected from reality, it's like being a red-uniformed, bit-character in Star Trek -- things aren't going to turn out well.

Case in point, when mortgagors and credit card companies stopped linking the borrowers' ability to re-pay to its lending standards, we got the financial system meltdown. Yesterday's market rally seems to be another serious disconnect. The S&P jumped 2.6% based on the highest increase in "consumer confidence" in 6 years. What the heck are consumers confident about? Housing hasn't bottomed out, credit card companies are chomping at the bit to screw-over responsible card users and GM is going to file BK. Oh yeah, and let's not forget the S&P may downgrade US debt.
If that weren't bad enough, looks like we're headed back to $3/gallon+ gas. I've been keeping track of my local Costco's prices since late July last year and I'm seeing an ominous trend.
Most experts do not believe the recent oil price increase is demand driven. But paper demands have increased inexplicably. This leads me to believe there's some sort of market manipulation by oil companies, refiners, hedge funds and/or other institutional investors.
Even assuming a real economic recovery is underway, I think that surging gas prices will squelch this fragile rebound. I don't know about you, but $3/gallon gas will cause me hardship. I know if it's going to cause me heartburn, it's gonna hurt others as well.
In November, I decided to start donating to charity regularly because my gas expenses went down significantly. Unfortunately, when gas hits $3/gallon, I will have to suspend my charitable giving.
Do you think gas will hit $3/gallon? What are you doing to prepare?
Update: According to this LA Times article, "Retail gasoline prices jumped by more than a dime over the last week in California and nationwide as oil rose to a new high for the year. But analysts had some reassuring words: Gas prices should be nearing their peak for the year, and a repeat of 2008's record run-up isn't anticipated." Uh-huh. We'll see.

Case in point, when mortgagors and credit card companies stopped linking the borrowers' ability to re-pay to its lending standards, we got the financial system meltdown. Yesterday's market rally seems to be another serious disconnect. The S&P jumped 2.6% based on the highest increase in "consumer confidence" in 6 years. What the heck are consumers confident about? Housing hasn't bottomed out, credit card companies are chomping at the bit to screw-over responsible card users and GM is going to file BK. Oh yeah, and let's not forget the S&P may downgrade US debt.
If that weren't bad enough, looks like we're headed back to $3/gallon+ gas. I've been keeping track of my local Costco's prices since late July last year and I'm seeing an ominous trend.
Date | $/Gallon |
7/28/08 | $4.16 |
8/12/08 | $3.94 |
8/21/08 | $3.82 |
9/8/08 | $3.68 |
9/16/08 | $3.62 |
9/29/08 | $3.48 |
10/8/08 | $3.34 |
10/15/08 | $3.26 |
10/23/08 | $3.03 |
11/7/08 | $2.46 |
11/22/08 | $1.85 |
11/22/08 | $1.85 |
11/29/08 | $1.79 |
11/30/08 | $1.96 |
12/4/08 | $1.69 |
12/16/08 | $1.59 |
12/20/08 | $1.76 |
12/30/08 | $1.68 |
1/12/09 | $1.90 |
1/26/09 | $1.98 |
2/13/09 | $2.20 |
2/26/09 | $2.16 |
3/10/09 | $2.10 |
3/24/09 | $2.08 |
4/1/09 | $2.18 |
4/18/09 | $2.20 |
4/29/09 | $2.28 |
5/6/09 | $2.30 |
5/13/09 | $2.40 |
5/20/09 | $2.49 |
Most experts do not believe the recent oil price increase is demand driven. But paper demands have increased inexplicably. This leads me to believe there's some sort of market manipulation by oil companies, refiners, hedge funds and/or other institutional investors.
Even assuming a real economic recovery is underway, I think that surging gas prices will squelch this fragile rebound. I don't know about you, but $3/gallon gas will cause me hardship. I know if it's going to cause me heartburn, it's gonna hurt others as well.
In November, I decided to start donating to charity regularly because my gas expenses went down significantly. Unfortunately, when gas hits $3/gallon, I will have to suspend my charitable giving.
Do you think gas will hit $3/gallon? What are you doing to prepare?
Update: According to this LA Times article, "Retail gasoline prices jumped by more than a dime over the last week in California and nationwide as oil rose to a new high for the year. But analysts had some reassuring words: Gas prices should be nearing their peak for the year, and a repeat of 2008's record run-up isn't anticipated." Uh-huh. We'll see.
Thursday, April 23, 2009
Admin Assistant's Day Gift Fail
Three of us in the office decided to give the admin assistants in our office boxes of awesome cookies from a local bakery. If Yelp opinions are any indication, they ARE quite killer. The cookies aren’t that cheap either. Each cookie costs $1.75 and a Baker’s half-dozen (i.e., 7 cookies) costs $9.75.

I collected money from my co-workers, purchased the cards, the cookies and wrapped the boxes in a cute cellophane wrapper. Split three ways, the three of us contributed about $10 each.
We presented the cookies to the first admin assistant who verbally thanked us. The second admin assistant didn’t come in until a couple of hours later so we left the cookies and card on her desk.
When the second admin assistant came in, I heard her say, “What’s this? Oh NOOOO!! Fatty food! I can’t eat THIS!” I heard the first admin assistant agreeing. The second admin assistant later sent an insincere thank-you email. When I walked by the first admin assistant’s desk later in the day, she said, “Oh, I’m trying not to touch the cookies.”
Okaaaay. Fine. I realize the cookies weren’t expensive and I (we) didn’t put much thought into it other than that I LOVE the cookies. And I also didn’t realize that either of these ladies was on a diet. After all, the first admin assistant is frequently eating local Mexican take-out. (Here's a diet tip: Cut out the daily breakfast burrito.) The second admin assistant previously brought supermarket brownies and day-old discount donuts to work, so how was I supposed to know?
These gals are certainly entitled to their opinions. After all, I too have received chintzy gifts and wondered, "WTF?" But I always kept my petty thoughts to myself.
 These are one of those moments where I just wanted to say, “Today is a bogus day where we have to thank you for doing a job that you're paid to do. If you don’t like the gifts, you gals should complain about it outside of our earshot. Better yet, you should’ve complained about how cheap we were on Twitter or on your blog.”
I don't know about you, but my $10 would've been better spent elsewhere. I swear. Sometimes I prefer the company of my cat versus my fellow human beings.
Thursday, April 16, 2009
This May Change What I’m Willing to Post On My Blog…
I started my blog as a way to memorialize how I deal with my personal finances – a kind of diary, if you will. My primary intent was to keep tabs on my spending, investments, savings and the progress on my debts. I also wanted a place I can store reference materials, such as interesting articles, great tips, etc.
But my blog has also evolved into an outlet where I air my thoughts, experiences and opinions (sometimes relating to PF matters only tangentially). It hasn’t all been pretty -- I’ve posted petty, elitist or mean-spirited rants that I can’t express in real-life to others. After all, what’s the purpose of a diary if you’re going to sugarcoat things?
Although many of my posts are personal in nature, I made the conscious choice to open my blog to the public because: (a) I write anonymously, (b) I don’t expect to have a wide-audience and (c) I enjoy receiving feedback (positive and negative) from my readers.
Consequently, I’ve been able to develop great relationships (albeit virtual) with people I would’ve otherwise never encountered. I’m grateful for all of the comments I’ve received. Even those that are critical have provided thoughtful, relevant, and civil opinions.
But a recent case decided by the California Appellate Court may change how and what I write in my blog in the future. The California Appellate Court recently held that a person who posts an article on the internet (e.g. blog or Myspace) does not have the right to state a cause of action for invasion of privacy when the post is republished. (Click here to read the opinion.)
In this case, a UC Berkeley student wrote a rather mean-spirited “ode” about her hometown and its residents in her Myspace journal. The student only identified herself by her first name and a picture. Six days later, the student removed the “ode” from her online journal. Before she took the “ode” down, the local high school principal submitted it to the local paper. The paper re-published the “ode” and attributed the authorship to the student, using her full name. (Note: Whatever point the editor wanted to make, couldn’t she have done it without identifying the author, especially since the offensive post was deleted? Or was the editor seeking retribution? Hmmm….)

The lunatic fringe of the student's hometown reacted violently by issuing death threats and shooting a gun at her family home. As a result, the student’s parents had to close their 20 year-old family business and move the heck out of Dodge. (Note: I wonder if the editor of the paper is proud of herself? And hasn’t this, ironically, lent credence to what the student wrote about the residents of the community? Hmmmm….)
I’m a firm believer that people need to accept the consequences for their actions and their words. But no one deserves to be threatened, physically or verbally, solely for their opinions, no matter how offensive. If the expressed opinion is libelous or slanderous, people should seek legal recourse.
I know of at least one blogger who shut down his blog after people tried to “out” him. (For what and to what end, I don’t know.) I know of other bloggers who’ve experienced something similar for expressing unpopular opinions about gift-giving etiquette or writing about her actions that some have deemed “morally reprehensible” (i.e., taking advantage of couponing rule loopholes). Seriously.
I guess what this means is that anything I write in this blog will be filtered and self-censored from hereon forward. Although it’s probably too late, I’m considering deleting prior posts that may be too revealing or potentially “offensive”.
But before I do, I just have to let out one dig: To all you nut-jobs who have nothing better to do than to “out” and seek retribution against an author for an “offensive” post, there is a better option -- You can stop reading the “offensive” blog and encourage others to do the same. There’s nothing worse to a blogger than having no audience.
So there. Bleh. [Note to self: Work on my filter…]
Wednesday, April 15, 2009
My Rant Against Tax Cheaters
I mailed in my taxes on Monday. I paid $50 to the Federal government and I paid $694 to the State of California. I would've owed much less had I not sold any of my company stocks last year. But I've reaped some nice gains, so it's only fair that I pay taxes on it. Besides, since I've held the stocks for over a year, I benefited from a lower capital gains tax rate.
And this leads me to my soapbox rant:
There is something wrong with our tax system, which allows people of means to manipulate their tax obligations through their claimed capital gains and capital losses. It's one thing to practice legally recognized tax avoidance (like selling stocks within a Roth IRA) and another to engage in tax evasion.
[Disclaimer: For obvious reasons, I am not going to go into specifics. Furthermore, I have no knowledge of anyone actually engaging in the conduct described below. This is just a general rant and is not directed at anyone in particular. Any resemblance of facts and circumstances to an actual person is pure coincidence. But if my rant hits home, I'm talkin' to YOU.]
And this leads me to my soapbox rant:
There is something wrong with our tax system, which allows people of means to manipulate their tax obligations through their claimed capital gains and capital losses. It's one thing to practice legally recognized tax avoidance (like selling stocks within a Roth IRA) and another to engage in tax evasion.
[Disclaimer: For obvious reasons, I am not going to go into specifics. Furthermore, I have no knowledge of anyone actually engaging in the conduct described below. This is just a general rant and is not directed at anyone in particular. Any resemblance of facts and circumstances to an actual person is pure coincidence. But if my rant hits home, I'm talkin' to YOU.]

Frankly, it's wrong of you to claim capital losses when in fact you haven't suffered any. And guess, what? Your reliance on a tax preparer really doesn't excuse you for claiming a loss that you haven't realized. You may have legal recourse against the tax preparer, but the bottomline is, it's your signature at the bottom of the tax form. YOU'RE responsible.
It's also wrong for you to out-and-out lie about your cost basis so that you can get a tax refund. And, no, ignorance of your true cost basis is never a defense. And besides, you're not ignorant -- your act is intentional. It's the difference of being stupid vs. a liar, and I know you're not stupid.
It's amusing (*NOT*) how you find burglary, shoplifting and any other forms of theft morally repugnant, yet have absolutely no problem evading taxes. Here's a newsflash: when you lie about your capital gains (or losses), you ARE indeed stealing from other taxpayers. If you owe it, pay it -- it's your obligation as a citizen.
And this whole argument by you and other like-minded people, that paying higher taxes is unpatriotic, is completely mind-boggling. You further justify your actions by claiming: (a) that the government is wasting taxpayer money, (b) you already pay enough tax and (c) rich people have other tax loopholes unavailable to the hoi poloi. Even assuming these arguments have any merit, which they do not, it's no excuse for lying on your tax return.
It is utterly hypocritical for you to accept the benefits of governement protection and programs, yet shirk paying your fair share of taxes. I understand that you don't like paying taxes. Neither do I. But guess what? To paraphrase Justice Oliver Wendell Homes, you pay for the privilege of living in a civilized society by paying taxes. (Justice Holmes' actual quote can be read here.) By evading taxes, YOU are unpatriotic, my friend.
And when you get audited (which I doubt you will), I won't be lending you a sympathetic ear but I'll try not to say, "I told you so."
Friday, April 10, 2009
Perhaps I HAVE Changed My Spendthrift Ways?
If you look at the details of my networth, you'll see that I have shloads of credit card debt. I wish I have a good excuse for it, but I don't. It was spent on designer purses, jewelry, fancy vacations,restaurants and shoes. You know, all necessities. ;-D
Although I strive to live a simpler and more frugal life, my spendthrift way is just lurking right below the surface. I have this nagging doubt that I haven't changed organically or internally at all. I can't help but to think that I'm only reacting to external factors, such as an impending layoff and my debts.
But something happened yesterday that made me think that perhaps I have changed. A SHOE EMERGENCY!! [Cue dramatic music.]

It happened near the end of the work day. I was walking, walking, walking until I heard a big crack and my left leg wobbled. Thank goodness (?) I have short legs and a low center of gravity since I would've otherwise done a face-plant.
Anyhow, the old Shtinky would've taken this as a true emergency. I would've left work early, headed to Nordstrom or Macy's to buy a replacement pair of shoes. $350 for a pair? Wow, that's expensive, but I have the credit-limit available! No problem!
And don't think the thought didn't cross my mind. In fact, I'm ashamed to admit I seriously PONDERED whether this qualified as an "emergency" thus allowing me to tap my emergency fund. After all, I AM at work and I shouldn't be walking around barefoot in the office, right?
Wrong. I sucked it up and taped up my heel. Can you see the clear tape around the left shoe in the picture?
Perhaps it wasn't really safe for me to walk around in the taped-up shoe, but how dangerous is it for me to walk from the office to my car to my apartment? Not much.
I'm proud to say, I've decided not to replace the shoe. I have several other similar style shoe in the same color. I'm seeing this as a good sign that I've changed my spendthrift ways. :-D
Okay, enough with patting myself on the back; I'm moving on to a rant.
I swear, I will never buy Jessica Simpson shoes ever again. It's not expensive but it's not cheap either. A shoe should last more than a couple of years, don't you think? I mean my Stuart Weitzman shoes have lasted me over 7 years! (It needs serious polishing, though. Heh heh.)
I guess this is a lesson learned: Buy good shoes, especially if you intend to wear them for a long time.
P.S. Hope you're all having a wonderful Passover and Good Friday. And have a wonderful Easter!
Subscribe to:
Posts (Atom)


